

Construction Firms Drive Surge In PGI
Applications for personal guarantee insurance from construction directors who would otherwise risk home, savings and other personal assets on loans has increased again in the past six months.
In just the last three months, application have risen 113% year on year.
This is according to new data from Purbeck Personal Guarantee Insurance. Applications were also 19% higher than in Q2.
When it comes to loans the business cannot repay, the lender can pursue the director's, even when the business is a limited company.
Borrowing more
Construction accounted for 18.1% of all applications to Purbeck in Q3, up from 13.8% a year earlier. In September 2026, the sector's share rose to more than one in five (20.4%), with applications up 153% on September 2025. With a quarter still to go, construction applications in 2026 are already 46% higher than the total for the whole of 2025.
Many contractors and smaller building firms have few physical assets to offer as security, so lenders ask for a personal guarantee instead. In Q3, more than half (51.5%) of construction applications were linked to unsecured loans, up 115% year on year.
The sums at stake are also rising. The average level of protection requested by construction firms rose 31% year on year to £232,993.
Working capital
Working capital remained the most common reason for borrowing, accounting for 46% of construction applications. That is down from 51% a year earlier, as borrowing for growth and development rose faster. Applications to fund investment in growth rose 167% year on year and now make up 16% of construction applications.
Todd Davison, Managing Director, Purbeck Personal Guarantee Insurance (PGI), said: "Construction firms are borrowing on a bigger scale. Applications for PGI from the sector have more than doubled in a year and construction firms are now asking for more cover than the average business.
"It is encouraging to see more firms borrowing to grow and to fund development, rather than only to manage cash flow. But most of this lending is unsecured, which means it is the director's personal guarantee and often their family home, that stands behind it.”
Risky business
Davison added: "Construction is a sector where one late payment or a failed project can put a business under pressure very quickly. Before signing a guarantee, directors should understand exactly what they could be liable for, take independent advice and think about how they would protect their personal assets if things went wrong."
Things to check
Whether the guarantee is capped at a fixed amount or unlimited.
Whether it is ‘joint and several ‘, meaning the lender can claim the full amount from any one guarantor.
Whether it covers only this loan or all current and future borrowing (an ‘all monies ‘[ guarantee).
How and when the guarantee can be released.
What protection is available if the business runs into difficulty.
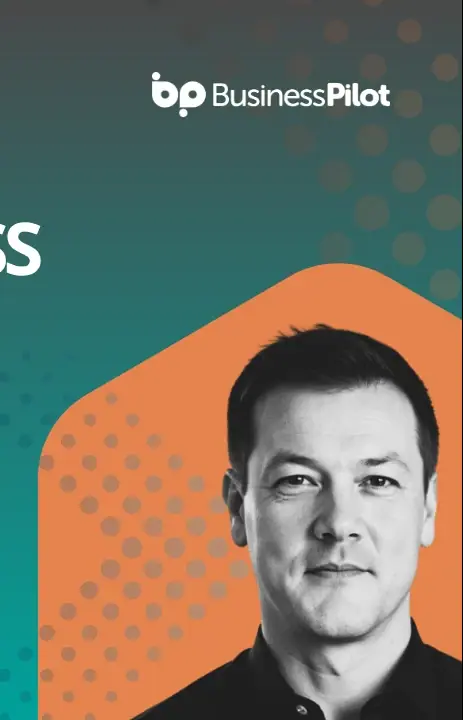
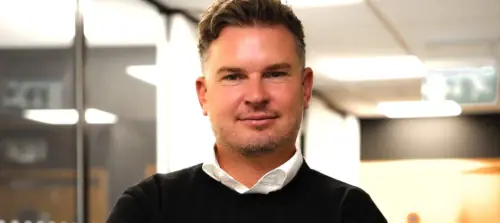
Picture: Todd Davison, the managing director of Purbeck Personal Guarantee Insurance.
Construction now accounts for almost one in five applications to Purbeck, as directors put their personal assets behind larger, mostly unsecured loans.
More To Read
Not All Rosy In The Garden Room Market
Don’t Dump Your Rep And Profits
Crippling Inflation Erodes Home Improvers’ Wages